Authors
Contents
Find out how we can help you navigate environmental markets
While carbon markets don’t form part of the main agenda at COP31, they are an important element of climate finance discussions being held amid a background of geopolitical tension. Greg Lydka Morris explains.
The 31st Conference of the Parties – COP31 – arrives at an interesting political time for climate change action after climate talks earlier in the year in Bonn ended in gridlock. Wider geopolitical tension hangs over Antalya, and climate has become a politicised issue in many countries with mainstream parties increasingly sceptical of climate action and national agendas watering down their climate commitments.
There may also be forthcoming delays on accessing the latest on climate change science. In the run up to COP31, an Intergovernmental Panel on Climate Change (IPCC) plenary session was suspended before timelines for the seventh comprehensive assessment on the state of the world’s climate (AR7) could be agreed. This could have implications for the COP process in future years, and follows reports that some countries were attempting to delay the publication of the report.
Meanwhile, the UN Environment Programme’s latest Emissions Gap Report for 2026 was published as normal in the run up to the conference, stating that that the world is on track to reach 2.6°C of warming this century under current climate policies.
To avoid this and limit the extent of the temperature ‘overshoot’ above 1.5°C (in a scenario where warming reaches 1.7°C by 2050 and then returns to or below 1.5°C by 2100) countries’ Nationally Determined Contributions (NDCs) need to be strengthened to reduce emissions by 69% on 2025 levels by 2040. Strengthened NDCs and the upcoming ‘global stocktake’, where global progress is assessed, will be critical to achieving this.
The broad agenda
COP31 opens in Antalya, Türkiye, on 9 November under a split leadership with Australia. Türkiye is hosting and setting the agenda, while Australia’s Minister for Climate Change and Energy Chris Bowen will steer the formal talks between countries as President of Negotiations.
New climate commitments are expected from heads of state and government at a leaders’ summit on 11 and 12 November. This follows the ‘Global Mutirão’ decision from COP30 in Belém, Brazil, which calls for efforts to triple adaptation finance by 2035 and the first UN dialogue on trade and climate.
Alongside the negotiations, the presidency is promoting its own Action Agenda, with a headline goal, ‘35 by 35’, to see commitment to lift electricity’s share of global final energy demand from just over 20% today to 35% by 2035. The case for the target is environmental, but with rising oil prices there is also a political and economic incentive for countries to diversify their energy mix.
What’s expected for Article 6?
When it comes to international carbon markets, the rulebooks for Article 6 of the Paris Agreement, which covers the trading of emissions reductions between countries, were finalised in 2024 and, since then, attention has moved to implementation, with rulebook review which may see meaningful change not scheduled until COP in 2028.
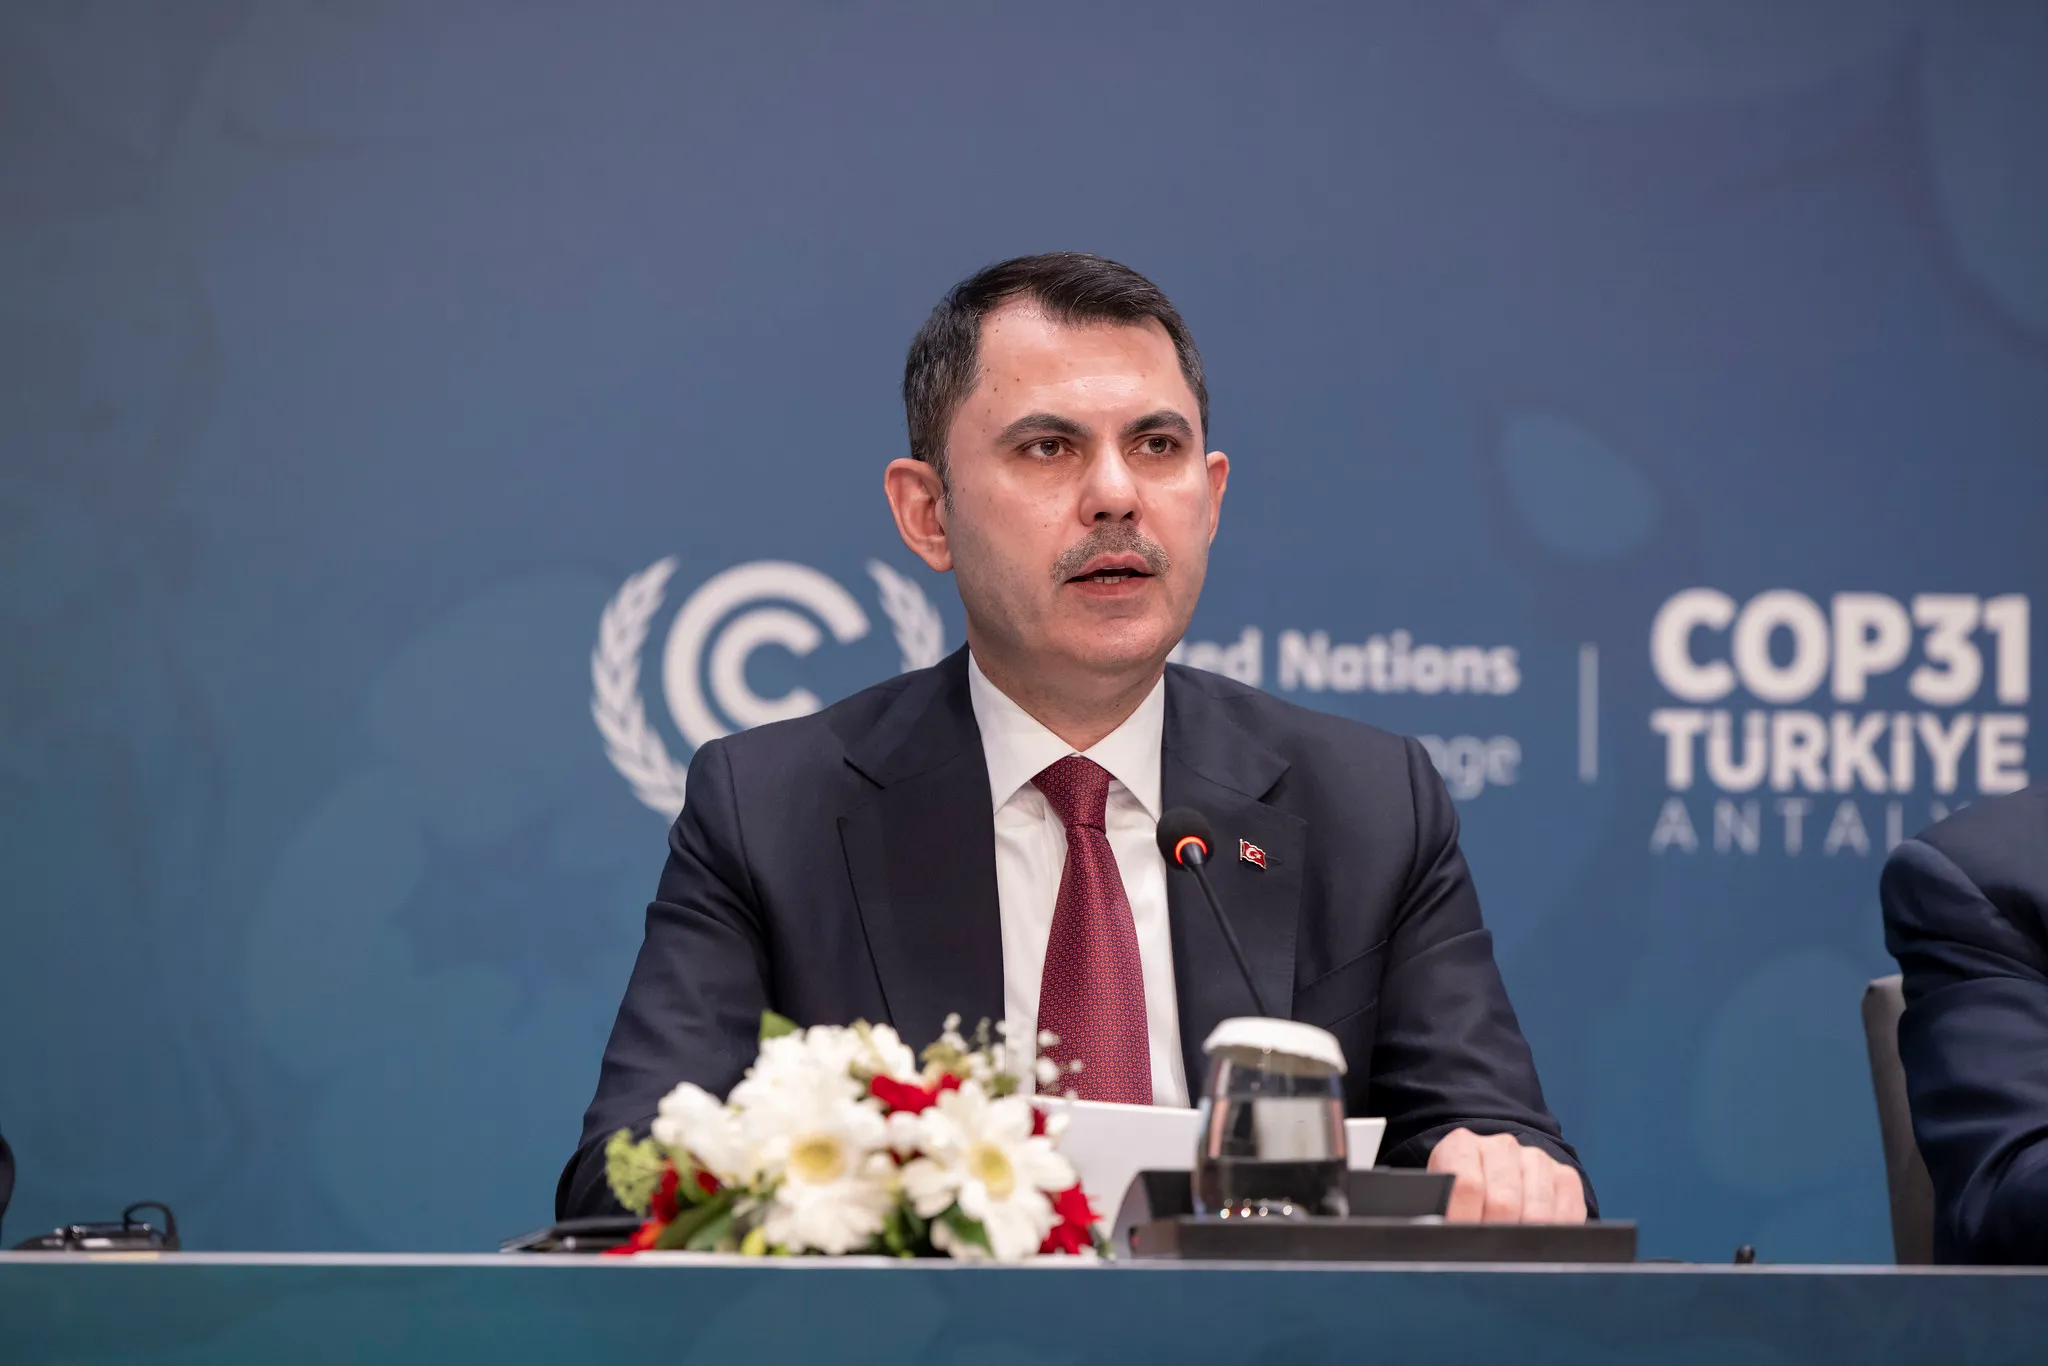
Türkiye’s Minister of Environment, Urbanisation and Climate Change and COP31 President, Murat Kurum, said in August that carbon markets will be a COP31 objective, and that governments should use them as a key climate finance channel to help mobilise more than $50bn a year in extra finance for developing economies. In this vein, Germany, which had previously pushed the EU to use international carbon credits to meet its emissions goals, has recently launched a tender for 1.1mn carbon credits from PACM to address emissions from government operations.
Türkiye joined the Coalition to Grow Carbon Markets earlier this year.
Discussions earlier this year in Bonn on Article 6 of the Paris Agreement, which covers the trading of emissions reductions between countries, concluded with confirmation of the wind-down of the Clean Development Mechanism (CDM), and an ask that the UN secretariat strengthens fundraising efforts to close the funding gap for implementing Article 6.2.
As with broader discussions on climate change mitigation and adaptation, funding will be a key topic of discussion for Article 6 at COP31. Countries still need to agree on how to fund the UN infrastructure supporting bilateral Article 6.2 deals (those occurring outside the central Article 6.4 Paris Agreement Crediting Mechanism (PACM)), including the registry, expert reviews of countries’ reporting, and capacity-building work. This currently faces a shortfall of $8mn to $9mn. PACM’s Methodological Expert Panel has also been constrained this year by financing shortfalls, which countries may address.
Two United Nations Framework Convention on Climate Change (UNFCCC) Secretariat reports will also be discussed in Türkiye. The first is its annual report on the implementation of Article 6.2 guidance, covering progress on infrastructure, reporting, technical reviews, and resources. The second is its annual compilation and synthesis of the Article 6 technical expert reviews, which identifies recurring findings, inconsistencies, and lessons learned. A review of the Article 6.8 programme on non-market approaches, which covers cooperation outside carbon trading, will also continue.
The PACM Supervisory Body will also submit its annual report for review. Progress this year has seen carbon crediting methodologies have now been confirmed for landfill gas, nitrous oxide from nitric acid production, grid-connected renewable electricity, more efficient wood and charcoal cookstoves, and cleaner, lower-emission household cooking. However, some developers and investors have already criticised the cookstove methodologies as too conservative and impractical.
More than 400 CDM activities have host-country approval to transition to Article 6. The first issuance, in February, went to a Myanmar cookstove programme that transitioned from the CDM. However, this is now receiving criticism over its ties to institutions controlled by Myanmar’s military junta, accusations of over-crediting, and weak stakeholder consultation.
Alongside these key events announcements from the sidelines will also impact carbon markets. Countries are likely to announce new regulations, sign bilateral agreements, and execute Letters of Authorisation.
What else is on the negotiating table?
As is usually the case, finance will play a key role in other negotiations, centring around Article 9 of the Paris Agreement. Article 9.1 says developed countries ‘shall provide’ finance to help developing countries cut emissions and adapt. Developing countries want the finance work programme launched at COP30 to focus squarely on Article 9.1 and to sit on the formal COP31 agenda, so wealthy countries are pressed to deliver public funding. Developed countries want a broader approach that includes private finance and contributions from richer developing economies such as China. A draft agenda in June left the item out, although the COP30 President has asked for it to be added.
Trade feeds into this. The EU’s Carbon Border Adjustment Mechanism (CBAM) charges importers for the carbon emitted in making goods such as steel, aluminium, and cement, and entered its definitive phase in January. Developing countries see it as costly and discriminatory, arguing it ignores the principle that richer countries should carry more of the climate burden. Russia has opened a formal World Trade Organization (WTO) dispute over it, and India and Indonesia have raised similar objections in WTO committees, while the EU defends it as WTO-compliant and as protection against carbon leakage.
Discussions at Bonn on climate and trade topics were conciliatory, but the issue may become a bigger fight in the negotiating rooms at COP31.
Adaptation will also be a key topic. UNEP estimates that developing countries need $310bn to $365bn a year for climate adaptation by 2035, against $26bn that was delivered in 2023. Talks in Bonn earlier this year stalled over finance, as developing countries wanted the pledge to triple adaptation finance written into the text on the Global Goal on Adaptation, while Canada, Japan, and Norway resisted, and countries disagreed on whether the taskforce building adaptation indicators should be run by experts or governments.
NDCs, transparency reports, and the global stocktake
Finally, COP31 also launches the second global stocktake, the five-yearly check on collective progress, which begins with information collection and runs until 2028. The stocktake may be complicated by the aforementioned IPCC delays in the build-up to the conference. The IPCC’s assessment reports are comprehensive scientific reviews published every five to seven years, providing countries with up-to-date science to set targets, shape policy, and assess the finance required. If AR7 is not in place by the conclusion of the stocktake, the process may have to rely on the Sixth Assessment Report, completed in 2023.
Countries are still filing their 2035 NDCs, with around 150 submitted to date. More will likely be submitted in the build-up to and during the conference.
Finally, second biennial transparency reports (BTRs), covering the years 2023 and 2024, are due by 31 December 2026. In these reports, countries set out their emissions, progress towards their NDCs, adaptation efforts, and the finance they give and receive every two years, and experts review them.
These are important for carbon markets – they record Article 6 activity, including the reporting of corresponding adjustments for that period. We expect much of the authorised volume, particularly from 2023 and 2024 vintages, to show up as corresponding adjustments in BTRs.
In summary, while carbon markets won’t play a central role in this COP, there will be some progress and they will permeate many discussions, not least on climate change finance. Given the broader backdrop, the intent, engagement, and outcomes of discussions in Antalya will tell us a lot about where COPs stand going forward and, more importantly, what they can achieve.
Keep up to date on the latest carbon market policy developments through Abatable's intelligence platform.